
If you cannot work because you are seriously injured or ill, disability insurance will provide you with a monthly, tax-free income to help replace your lost wages. An injury does not have to be as blatant as a broken leg or arm – suffering from chronic pain or dealing with mental health issues can also qualify you for a disability insurance payout.
Why do I need disability insurance?
Unfortunately, people become disabled – whether temporarily or permanently – quite often. In 2017, over 20 percent of Canadians had one or more disabilities.
If you’re disabled, you may lose one of your most valuable assets – your ability to work and bring in a paycheck. Disability insurance can help replace that paycheck for as long as you need it to. Being able to rely on a disability insurance payout means you won’t have to dip into your savings if anything happens to you.
Disability insurance is especially important if you are self-employed, particularly if you are the family’s sole income earner.
What if I already have disability insurance through work?
If you have disability insurance through work, that’s great – but it may not replace 100 percent of your paycheck, especially if you’re off work for a long time. If you purchase private disability insurance, you can:
Having private disability insurance will give you peace of mind that you either have additional coverage if you are employed and at least some disability coverage if you lose your job.
How does disability insurance work?
We’d be happy to answer any questions you have about disability insurance. There are five main steps to disability insurance:
We’re Here To Help
If you’d like to know more about disability insurance – from how much it would cost you to what you can file a claim for – we’re here to help! Give us a call today.
Taking charge of your family’s financial well-being through effective budgeting is a crucial step in securing a brighter future. We’ll explore the significance of budgeting and provide practical tips to help you manage your money wisely while ensuring the best possible support for your loved ones, including those with disabilities and their Registered Disability Savings Plan (RDSP).
Why Budgeting Matters for Families
Budgeting is a powerful financial tool that holds importance for all families:
Steps to Effective Budgeting for Families
Tips for Successful Budgeting
Budgeting is your family’s pathway to financial security and ensuring a brighter financial future. By budgeting wisely and prioritizing your loved one’s financial well-being, you can control your family’s finances, reduce stress, and work towards a future filled with financial peace of mind. Remember, financial success for families means making informed choices that align with your values and aspirations. Start budgeting today to achieve financial wellness for your entire family, balancing the needs of all family members, including those who rely on the support of the RDSP.
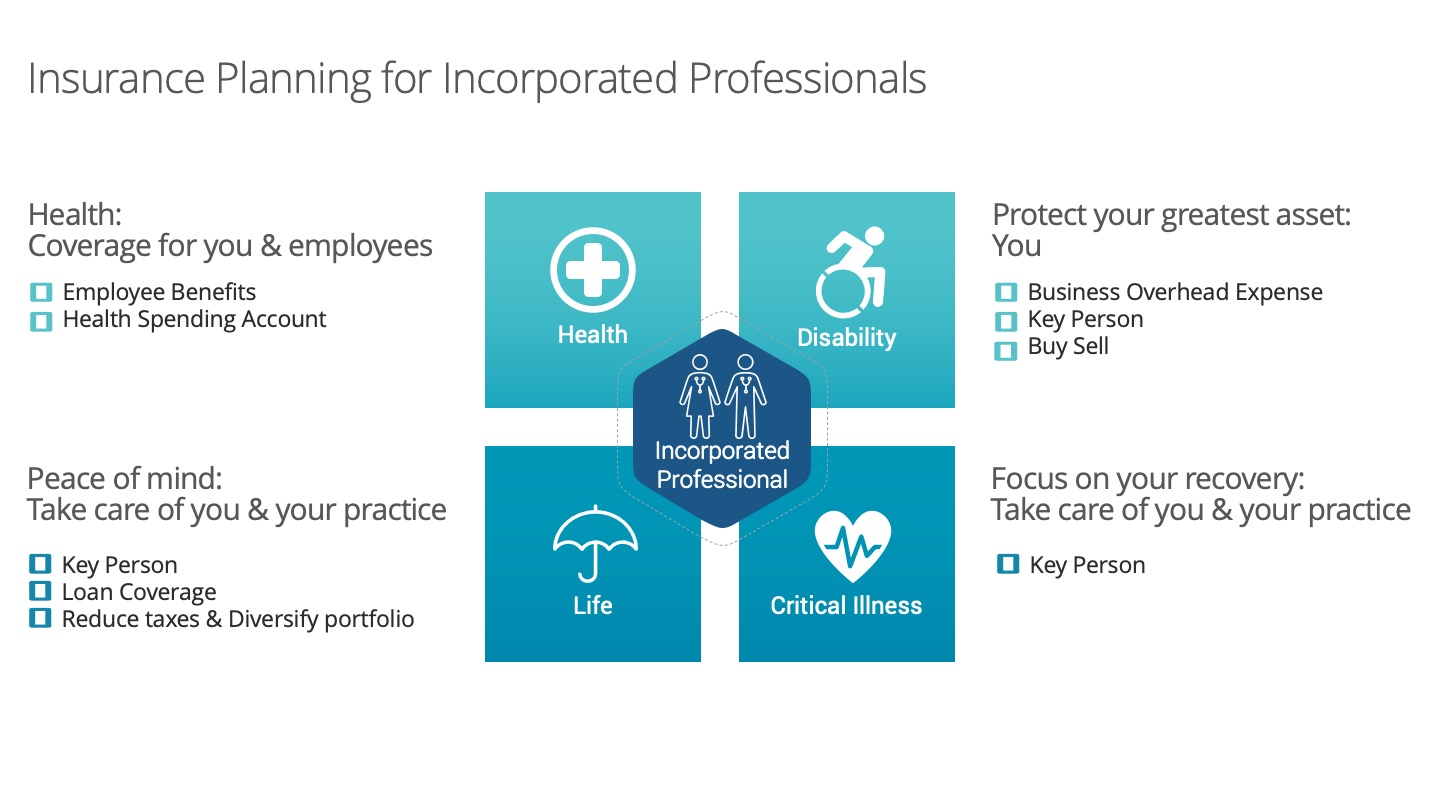
For incorporated professionals, making sure your practice is financially protected can be overwhelming. Incorporated professionals face a unique set of challenges when it comes to managing risk. Insurance can play an important role when it comes to reducing the financial impact on your practice in the case of uncontrollable events such as disability, or critical illness. This infographic and article address the importance of corporate insurance.
The 4 areas of insurance a incorporated professional should take care of are:
Health
Disability
Critical Illness
Life
Health: We are fortunate in Canada, where the healthcare system pays for basic healthcare services for Canadian citizens and permanent residents. However, not everything healthcare related is covered, in reality, 30% of our health costs* are paid for out of pocket or through private insurance such as prescription medication, dental, prescription glasses, physiotherapy, etc.
For incorporated professionals, offering employee health benefits make smart business sense because health benefits can form part of a compensation package and can help retain key employees and attract new talent.
For incorporated professionals that are looking to provide alternative health plans in a cost effective manner, you may want to consider a health spending account.
Disability: Most people spend money on protecting their home and car, but many overlook protecting their greatest asset: their ability to earn income. Unfortunately one in three people on average will be disabled for 90 days or more at least once before the age of 65.
Consider the financial impact this would have on your practice if you or a key employee were to suffer from an injury or illness. Disability insurance can provide a monthly income to help keep your practice running.
Business overhead expense insurance can provide monthly reimbursement of expenses during total disability such as rent for commercial space, utilities, employee salaries and benefits, equipment leasing costs, accounting fees, insurance premiums for property and liability, etc.
Key person disability insurance can be used to provide monthly funds for you or key employee while they’re disabled and protect the business from lost revenue while your business finds and trains an appropriate replacement.
Critical Illness: For a lot of us, the idea of experiencing a critical illness such as a heart attack, stroke or cancer can seem unlikely, but almost 3 in 4 (73%) working Canadians know someone who experience a serious illness. Sadly, this can have serious consequences on you, your family and business, with Critical Illness insurance, it provides a lump sum payment so you can focus on your recovery.
Key person critical illness insurance can be used to provide funds to the practice so it can supplement income during time away, cover debt repayment, salary for key employees or fixed overhead expenses.
Buy sell critical illness insurance can provide you with a lump sum payment if your business partner or shareholder were to suffer from a critical illness. These funds can be used to purchase the shares of the partner, fund a buy sell agreement and reassure creditors and suppliers.
Life: For an incorporated professional, not only do your employees depend on you for financial support but your loved ones do too. Life insurance is important because it can protect your practice and also be another form of investment for excess funds.
Key person life insurance can be used to provide a lump sum payment to the practice on death of the insured so it can keep the business going until you an appropriate replacement is found. It can also be used to retain loyal employees by supplying a retirement fund inside the insurance policy.
Loan coverage life insurance can help cover off any outstanding business loans and debts.
Reduce taxes & diversify your portfolio, often life insurance is viewed only as protection, however with permanent life insurance, there is an option to deposit excess funds not needed for operations to provide for tax-free growth (within government limits) to diversify your portfolio and reduce taxes on passive investments.
Talk to us to make sure you and your practice are protected.
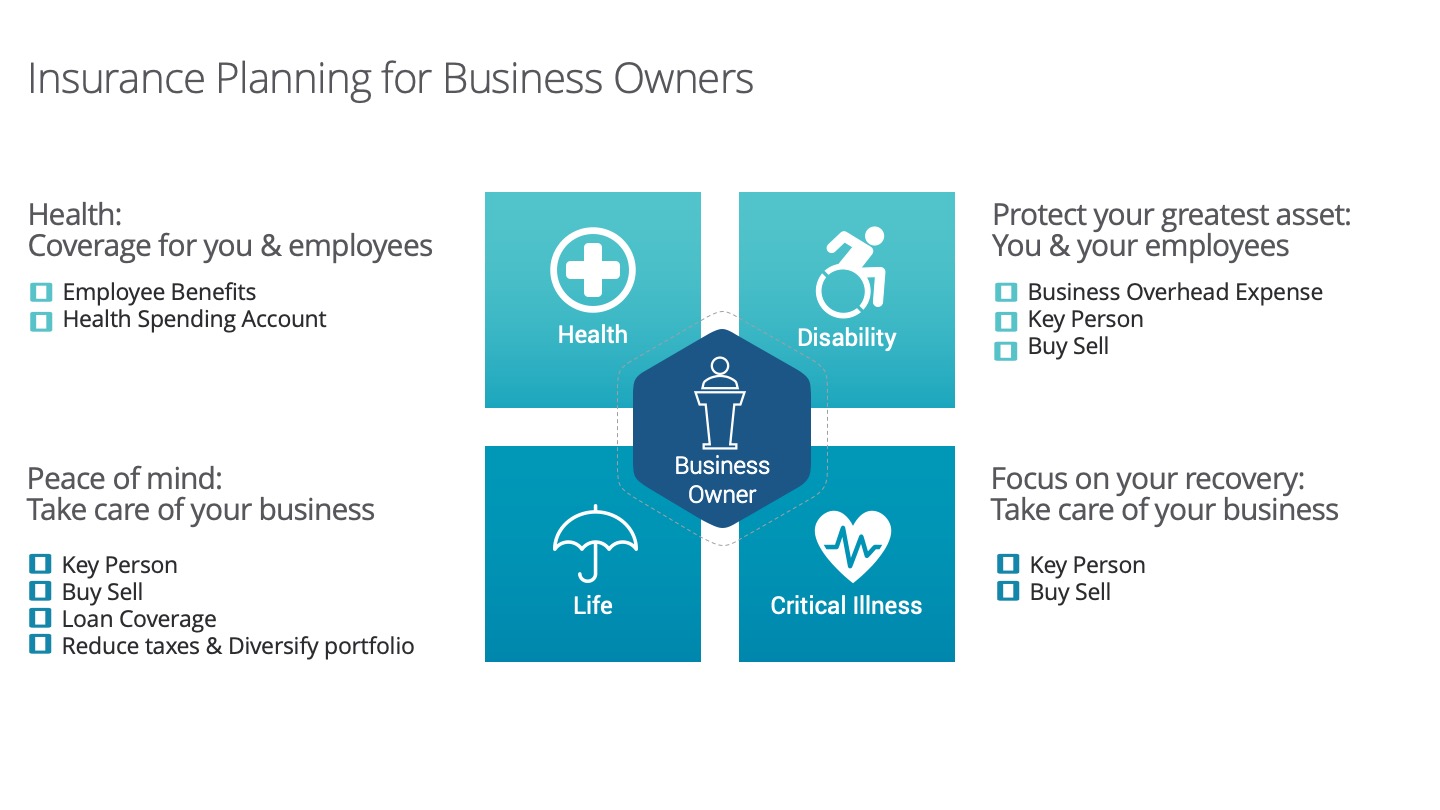
For business owners, making sure your business is financially protected can be overwhelming. Business owners face a unique set of challenges when it comes to managing risk. Insurance can play an important role when it comes to reducing the financial impact on your business in the case of uncontrollable events such as disability, critical illness or loss of a key shareholder or employee.
This infographic addresses the importance of corporate insurance.
The 4 areas of insurance a business owner should take care of are:
Health
Disability
Critical Illness
Life
Health: We are fortunate in Canada, where the healthcare system pays for basic healthcare services for Canadian citizens and permanent residents. However, not everything healthcare related is covered, in reality, 30% of our health costs* are paid for out of pocket or through private insurance such as prescription medication, dental, prescription glasses, physiotherapy, etc.
For business owners, offering employee health benefits make smart business sense because health benefits can form part of a compensation package and can help retain key employees and attract new talent.
For business owners that are looking to provide alternative health plans in a cost effective manner, you may want to consider a health spending account.
Disability: Most people spend money on protecting their home and car, but many overlook protecting their greatest asset: their ability to earn income. Unfortunately one in three people on average will be disabled for 90 days or more at least once before the age of 65.
Consider the financial impact this would have on your business if you, a key employee or shareholder were to suffer from an injury or illness. Disability insurance can provide a monthly income to help keep your business running.
Business overhead expense insurance can provide monthly reimbursement of expenses during total disability such as rent for commercial space, utilities, employee salaries and benefits, equipment leasing costs, accounting fees, insurance premiums for property and liability, etc.
Key person disability insurance can be used to provide monthly funds for the key employee while they’re disabled and protect the business from lost revenue while your business finds and trains an appropriate replacement.
Buy sell disability insurance can provide you with a lump sum payment if your business partner were to become totally disabled. These funds can be used to purchase the shares of the disabled partner, fund a buy sell agreement and reassure creditors and suppliers.
Critical Illness: For a lot of us, the idea of experiencing a critical illness such as a heart attack, stroke or cancer can seem unlikely, but almost 3 in 4 (73%) working Canadians know someone who experience a serious illness. Sadly, this can have serious consequences on you, your family and business, with Critical Illness insurance, it provides a lump sum payment so you can focus on your recovery.
Key person critical illness insurance can be used to provide funds to the company so it can supplement income during time away, cover debt repayment, salary for key employees or fixed overhead expenses.
Buy sell critical illness insurance can provide you with a lump sum payment if your business partner or shareholder were to suffer from a critical illness. These funds can be used to purchase the shares of the partner, fund a buy sell agreement and reassure creditors and suppliers.
Life: For a business owner, not only do your employees depend on you for financial support but your loved ones do too. Life insurance is important because it can protect your business and also be another form of investment for excess company funds.
Key person life insurance can be used to provide a lump sum payment to the company on death of the insured so it can keep the business going until you an appropriate replacement is found. It can also be used to retain loyal employees by supplying a retirement fund inside the insurance policy.
Buy sell life insurance can provide you with a lump sum payment if your business partner or shareholder were to pass away. These funds can be used to purchase the shares of the deceased partner, fund a buy sell agreement and reassure creditors and suppliers.
Loan coverage life insurance can help cover off any outstanding business loans and debts.
Reduce taxes & diversify your portfolio, often life insurance is viewed only as protection, however with permanent life insurance, there is an option to deposit excess company funds not needed for operations to provide for tax-free growth (within government limits) to diversify your portfolio and reduce taxes on passive investments.
Talk to us about helping making sure you and your business are protected.
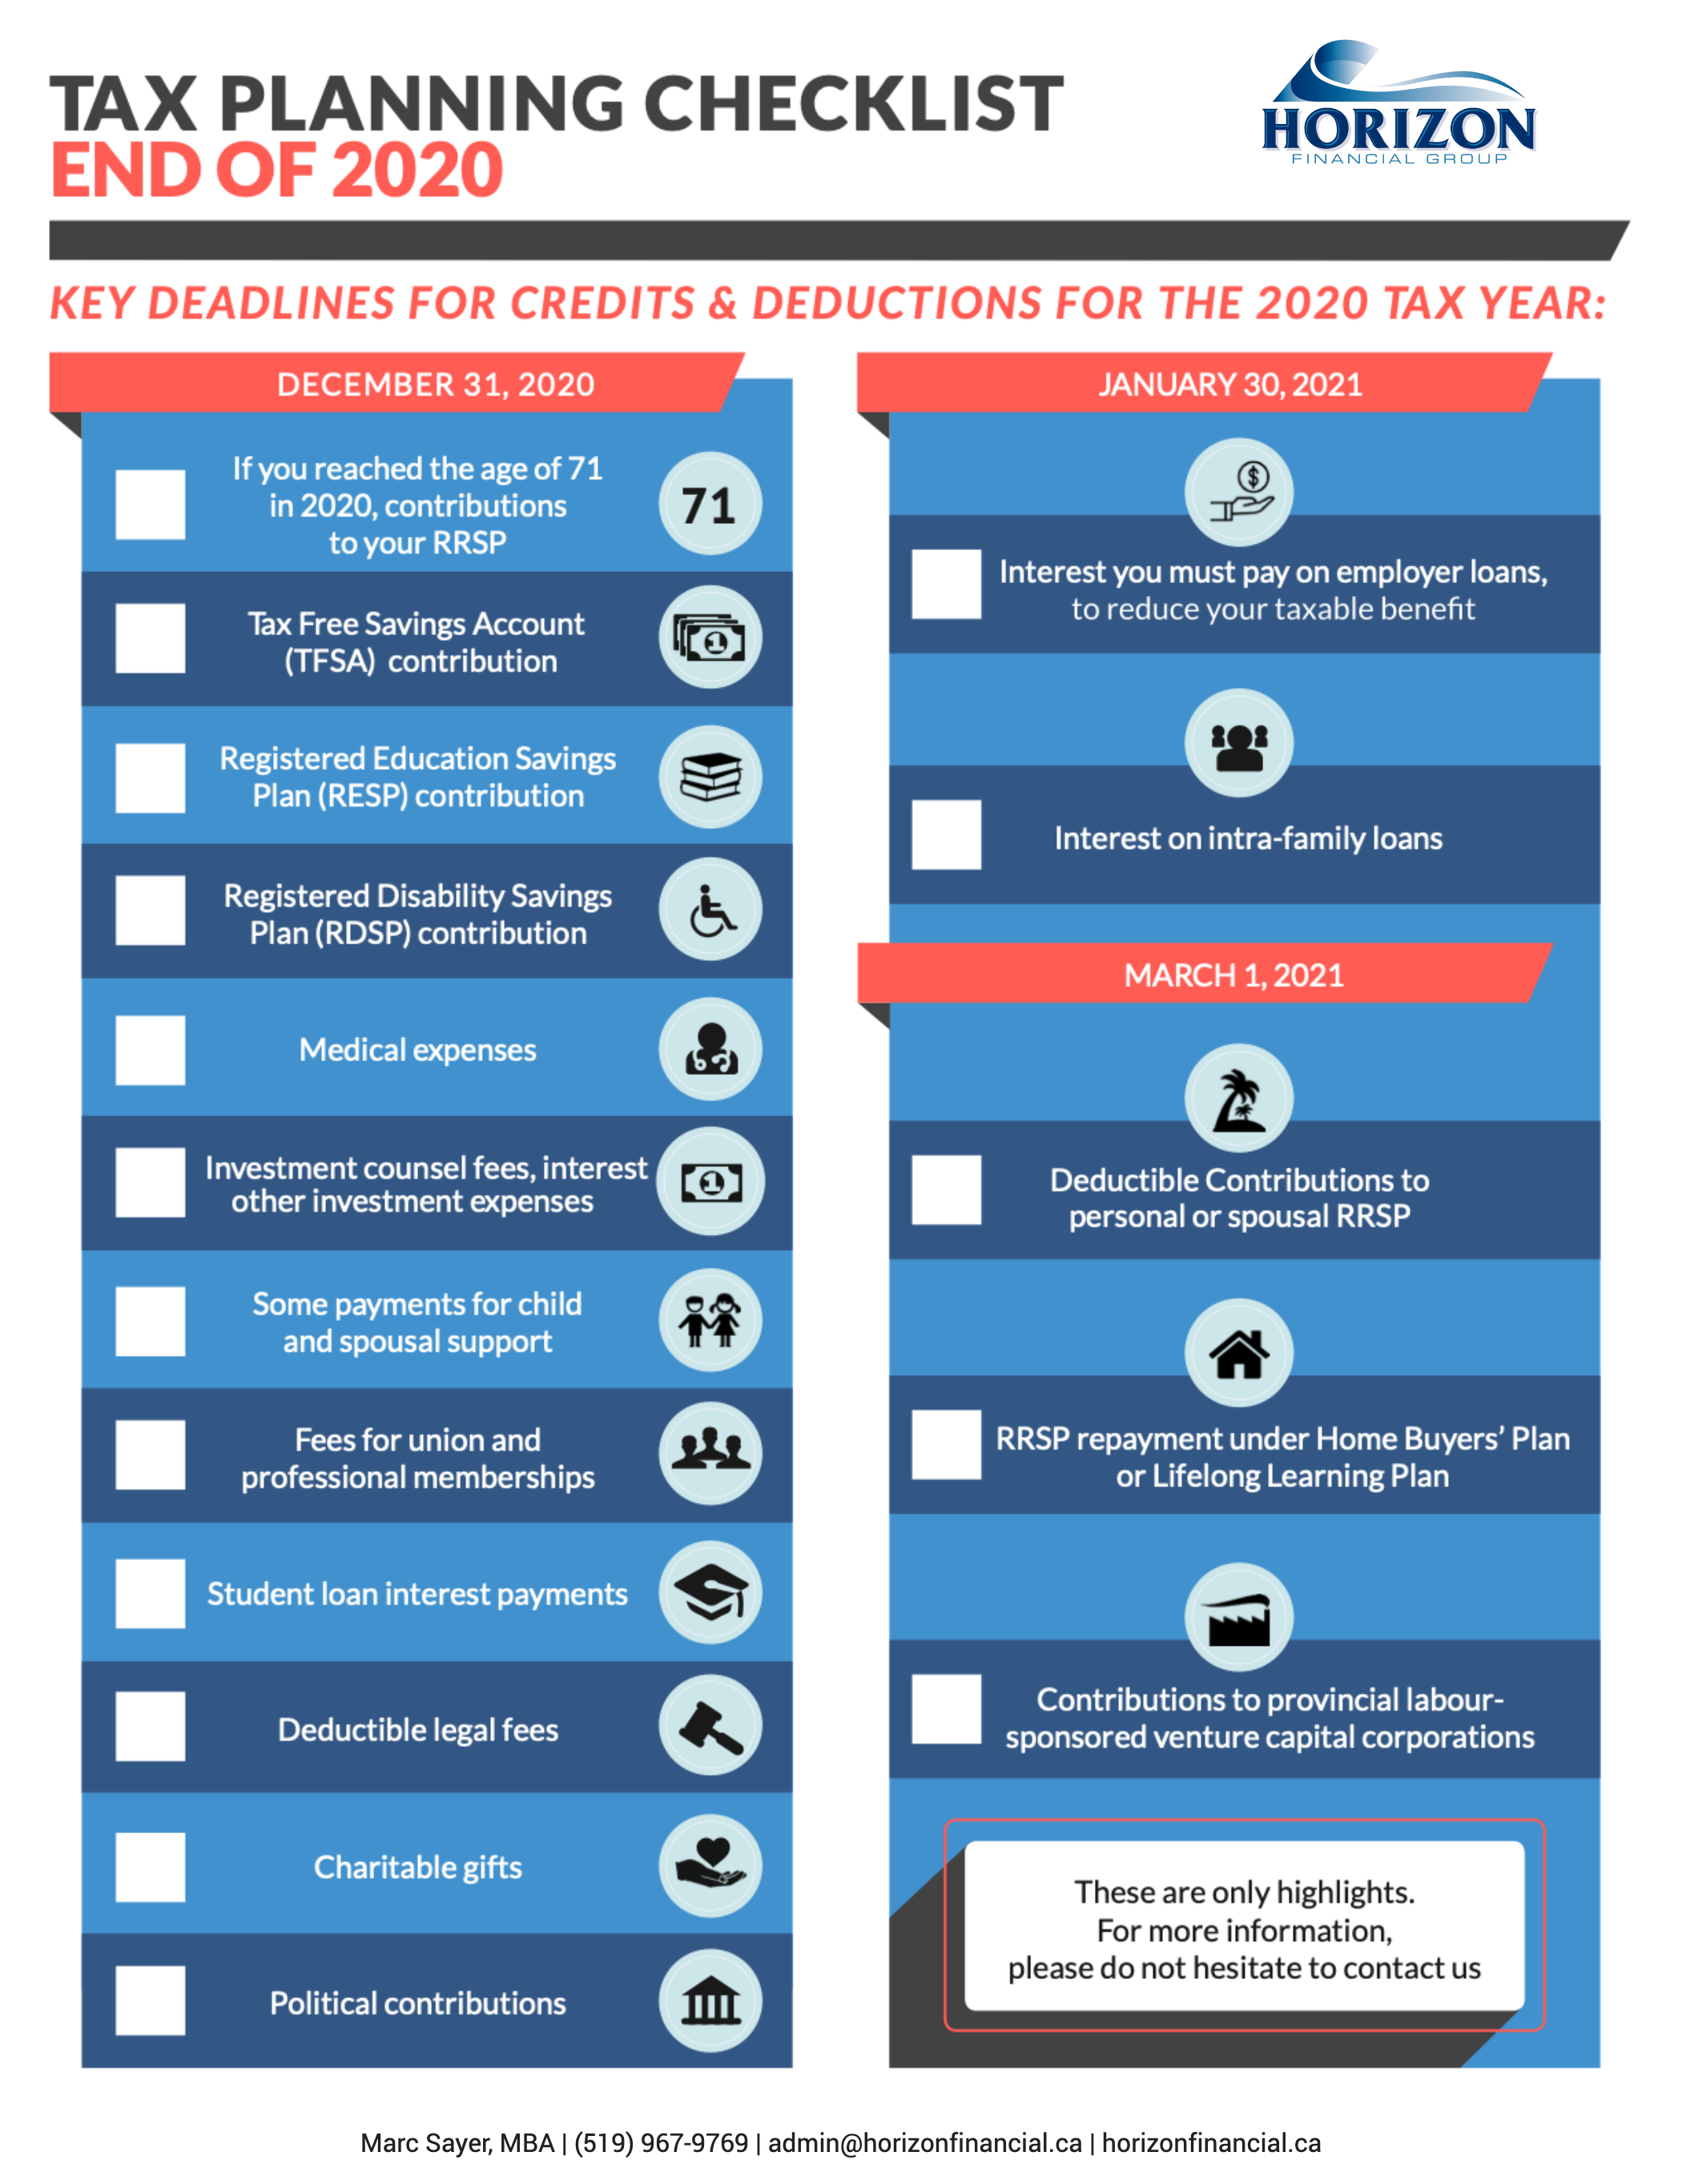
Now that we are reaching the end of the tax year, it’s an excellent time to review your finances. We’ve listed below some of the critical areas to consider and provide you with useful guidelines.
We have divided our tax planning tips into five sections:
Tax Deadlines
Individual tax issues
Family tax issues
Managing your investments
Retirement planning
December 31, 2020:
If you reached the age of 71 in 2020, you can’t contribute to your RRSP after this date
Use up your TFSA contribution room
Contribute to an RESP to get the Canadian Education Savings Grant (CESG) and the income-tested Canada Learning Bond (if eligible).
Contribute to an RDSP to get the Canada Disability Savings Grant (CDSG) and the income-tested Canada Disability Savings Bond (if eligible).
Medical expenses
Investment counsel fees, interest and other expenses relating to investments
Some payments for child and spousal support
Fees for union and professional memberships
Student loan interest payments
Deductible legal fees
Charitable gifts
Political contributions
January 30, 2021
Interest on intra-family loans
The interest you must pay on employer loans to reduce your taxable benefit
March 1, 2021
Contributions to provincial labour-sponsored venture capital corporations
RRSP Repayment under Home Buyers Plan or Lifelong Learning Plan
Deductible contributions to a personal or spousal RRSP
To help Canadians deal with financial hardships due to job loss because of COVID-19, the Canadian government introduced several benefit programs. If you received any of these benefits, you should be aware of the tax ramifications.
The Canada Emergency Response Benefit (CERB) was the first benefit program issued by the government and ran until September 26, 2020. If you received the CERB at all during 2020, the government will issue you at T4A, showing how much money you received from the CERB program. You must then declare that as income when filing your 2020 income tax return. Since no tax was taken off at the source, be sure to put aside money to pay for potential income taxes on your CERB income.
As of September 27, 2020, the government offered three replacement benefit programs:
Canada Recovery Benefit (CRB)
This is for people impacted by COVID-19 who work but are not eligible for EI (e.g. self-employed).
Canada Recovery Sickness Benefit (CRSB)
This is for people who are employed cannot work due to COVID-19 and do not have access to paid sick leave.
Canada Recovery Caregiving Benefit (CRCB)
This is for people who must miss work to care for a family member who has COVID-19.
For all three of these programs, the government will be withholding 10% in taxes upfront, but you may end up owing extra tax, depending on the rest of your income for 2020, so it’s important to set extra money aside for taxes.
Also, there is a unique condition for the CRB only. If you make over $38,000 in 2020 (excluding the CRB), you will have to pay back the CRB at a rate of 50 cents for each dollar of CRB you earned above the threshold.
If you paid interest on an eligible student loan in 2020, you can claim a non-refundable tax credit in the amount of interest you paid by December 31. In addition, you should be aware that student loan payments were frozen for six months – from March 30 to September 30. No interest accrued on student loans during that period.
Check your eligibility for the Canada Child Benefit
(CCB)
To receive the Canada Child Benefit in 2021/22, you need to file your tax returns for 2020 as the benefit is calculated using your family income from the previous year. Eligibility for the CCB depends on set criteria such as your family’s income, how many children you have, and how old they are. You may qualify for a full or partial amount, depending on whether you have full custody or shared custody.
Consider family income splitting
The CRA offers a prescribed low-interest rate on family loans. Therefore, it makes sense to consider setting up an income splitting loan arrangement with your family members. If you do this, you can potentially lock in a family loan at a low-interest rate of 1% and then invest the borrowed money into a higher return investment while benefitting from your family member’s lower tax status. Don’t forget to adhere to the Tax on Split Income rules.
Use up your TFSA contribution room
If you can, it’s worth contributing the full $6,000 to your TFSA for 2020. You can also contribute more (up to $69,500) if you are 29 or older and haven’t made any previous TFSA contributions.
Contribute to a Registered Education Savings Plan (RESP)
The Registered Education Savings Plan (RESP) is a savings plan for parents and others to save for a child’s education. The Canada Education Savings Grant (CESG) will match up to 20% of your contributions up to a maximum of $2,500.
That means the CESG can add a maximum of $500 to an RESP each year. The grant room accumulates until your child turns 17. Therefore, any unused CESG amounts for the current year are automatically carried forward for possible use in the future years.
The income-tested Canada Learning Bond (CLB) is paid directly to a child’s RESP by the Canadian government to low-income families. No personal contributions are required to receive the CLB.
Contribute to a Registered Disability Savings Plan (RDSP)
The Registered Disability Savings Plan (RDSP) is a savings plan for parents and others to save for the financial security of a person who is eligible for the Disability Tax Credit (DTC). The government will pay a matching Canada Disability Savings Grant (CDSG) up to 300% – depending on the beneficiary’s adjusted family net income and amount contributed.
Also, low-income Canadians with disabilities may be eligible for a Canada Disability Savings Bond (CDSB). If you qualify, it will be paid directly to your RDSP.
The government will pay matching grants or bonds into the RSDP up to and including the end of the year the recipient turns 49. Be aware that there is a 10-year carry-forward of CDSG and CDSB entitlements.
Donate securities to charity
Donating by year-end will provide you with tax savings. If you donate eligible securities or mutual funds, capital gains tax does not apply, and you can receive a tax receipt for their full market value. Also, the charity gets the full value of the securities.
Think about selling any investments with unrealized capital losses
It might be worth doing this before year-end to apply the loss against any net capital gains achieved during the last three years. The last trading date for 2020 for Canadian and US publicly traded stocks will be Tuesday December 29th in order to record the gain or loss in the 2020 taxation year.
Conversely, if you have investments with unrealized capital gains that cannot be offset with capital losses, it may be worth selling them after 2020 to be taxed on the income the following year.
Consider the timing of purchasing of certain non-registered investments
Suppose you are considering purchasing an interest-bearing investment like a guaranteed investment certificate (GIC) with a maturity date of one year or more. In that case, you may consider delaying the purchase to the following year, so you don’t have to pay tax on accrued interest until 2021. You should also consider this with mutual funds that make taxable distributions before the end of 2020, consider delaying this until early 2021. Don’t pay taxes earlier than necessary.
Check if you have investments in a corporation
The new passive investment income rules apply to tax years from 2018 onwards. They state that the small business deduction is reduced for companies with between $50,000 and $150,000 of investment income. Therefore, the small business deduction has entirely stopped for corporations that earn a passive investment income of more than $150,000.
Note – At a provincial level, both Ontario and New Brunswick do not follow the federal rules to limit access to the small business deduction.
Make the most of your RRSP
The deadline for making contributions to your RRSP for the year 2020 is March 1, 2021. The deduction limit for 2020 is limited to 18% of the income you earned in 2020, to a maximum of $27,230. This maximum amount is impacted by the following:
Any pension adjustment
Any previous unused RRSP contribution room
Any pension adjustment reversal.
Remember that deducting your RRSP contribution reduces your after-tax cost of making said contribution.
Check when your RRSP is due to end
If you reach the age of 71 during 2020, you must wind up your RRSP this year. You must make your final contribution to it by December 31, 2020.
Convert to RRIF before year-end
If you turned 65 during 2020 or are already older than 65, you’re entitled to a pension credit that can fully or partly offset the tax on the first $2,000 of eligible income annually. Consider setting up an RRIF before year-end to pay out $2,000 annually if you don’t have any other eligible pension income.
If you have any questions about your taxes for 2020, contact us – we can help you!


Insurance products, including segregated fund policies, are offered through Horizon Financial Group, and Financial Advisors Marc Sayer, Valerie Sayer and Conner Anastasakos offer mutual funds through IPC Wealth Inc. IPC Wealth Inc. is a member of CIRO and the Canadian Investor Protection Fund.
Any activity in relation to titles of President, Chief Investment Officer and Vice-President of Horizon Financial Group is related to insurance business only and is not the business of/or under the supervision of IPC Wealth Inc.
IPC Wealth and design are trademarks of Investment Planning Counsel Inc. and used under license by IPC Wealth Inc.